
Coverage We Offer
Compare home, auto, flood, umbrella, and business insurance options. As an independent agency, we shop multiple carriers to find the right fit.
Umbrella Insurance
State minimum auto liability limits were not designed to handle real accidents. A serious at-fault accident can generate $500,000 or more in damages. A personal umbrella adds $1M to $5M of liability coverage above your home and auto policies for a few hundred dollars per year.
Condo Insurance
Your association has a master policy on the building, but it stops at your unit. Condo insurance covers the interior, your belongings, your liability, and the gap between what the master policy pays and what you actually need to repair your unit.
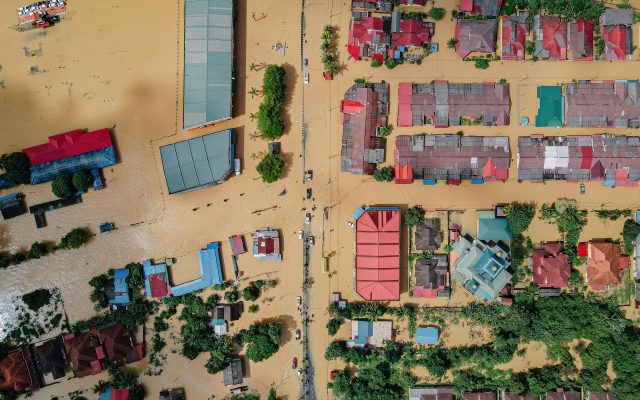
Flood Insurance
Standard homeowners and commercial property policies exclude flood damage. Localized storms regularly flood properties that FEMA does not classify as high-risk. Flood insurance is a separate policy through the federal NFIP program or a private flood insurer.
Landlord Insurance
The moment a tenant moves in, your standard homeowners policy stops covering the property. Landlord insurance covers the building, lost rent if a covered loss displaces tenants, and your liability as a property owner.
Jewelry Insurance
A standard homeowners or renters policy typically limits jewelry coverage to $1,500 for theft. An engagement ring, watch, or family heirloom worth $5,000 or more needs to be scheduled separately. Scheduled articles coverage insures the item specifically, at its agreed value, with no depreciation.
Motorcycle Insurance
Motorcycles are not covered under personal auto policies. Almost every state requires a separate motorcycle policy with at least minimum liability limits. Coverage gaps are common because medical costs from a motorcycle accident are higher and riders are more exposed than drivers.
Collector Auto Insurance
A standard auto policy pays actual cash value which accounts for depreciation. For a 1967 Mustang or a low-mileage exotic that has appreciated, actual cash value is wrong. Collector car insurance uses agreed value so you know exactly what you will recover if the car is totaled.
Farm and Rural Property Insurance
Standard homeowners policies are built for suburban homes. A farm or rural property has outbuildings, equipment, livestock, and exposures that a standard homeowners policy does not cover. Farm and ranch insurance is a separate product built for working land.
Home Business Insurance
About 16 million Americans operate businesses from home. A standard homeowners policy excludes business property above a low threshold and provides no business liability coverage at all. If you run any commercial activity from your home you need a separate business policy or endorsement.
Scheduled Personal Property Insurance
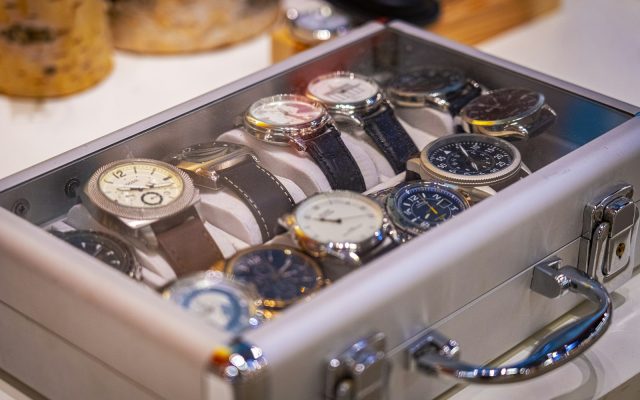
Standard homeowners and renters policies cover personal property as a group up to a total limit, with sublimits for specific categories. Cameras, musical instruments, sports equipment, and collectibles often exceed these sublimits. A scheduled articles rider or standalone policy covers each item individually at its agreed value.